This Week at a Glance
Last issue we warned against reading a falling oil price as a falling risk premium. This week proves the point. Brent has round-tripped back above US$87/bbl — up over twelve percent from the 5 August close — as the reported Hormuz de-escalation has stalled and Iran has said the Strait will stay closed until the US meets its conditions. More significantly, the US naval blockade against Iranian ports that began in mid-July has turned kinetic: a US Navy helicopter fired on a Panama-flagged container ship bound for Iran on 11 August, and Hormuz transits have fallen to just 16 ships a day. Gard P&I has pulled war-risk cover across the Indian Ocean, Gulf of Aden and Red Sea effective 16 August. For Southeast Asian operators, this is the scenario Issue 002 flagged as the downside risk — it has now arrived. Insurance, routing and counterparty screening need to be re-verified this week, not assumed current.
- Oil: Brent US$87.05/bbl and WTI US$81.25/bbl on 13 August, up sharply from the US$79.42/US$75.14 close on 5 August as Hormuz peace hopes fade and the EIA raises its Brent outlook to US$87/b on Hormuz shipping constraints.
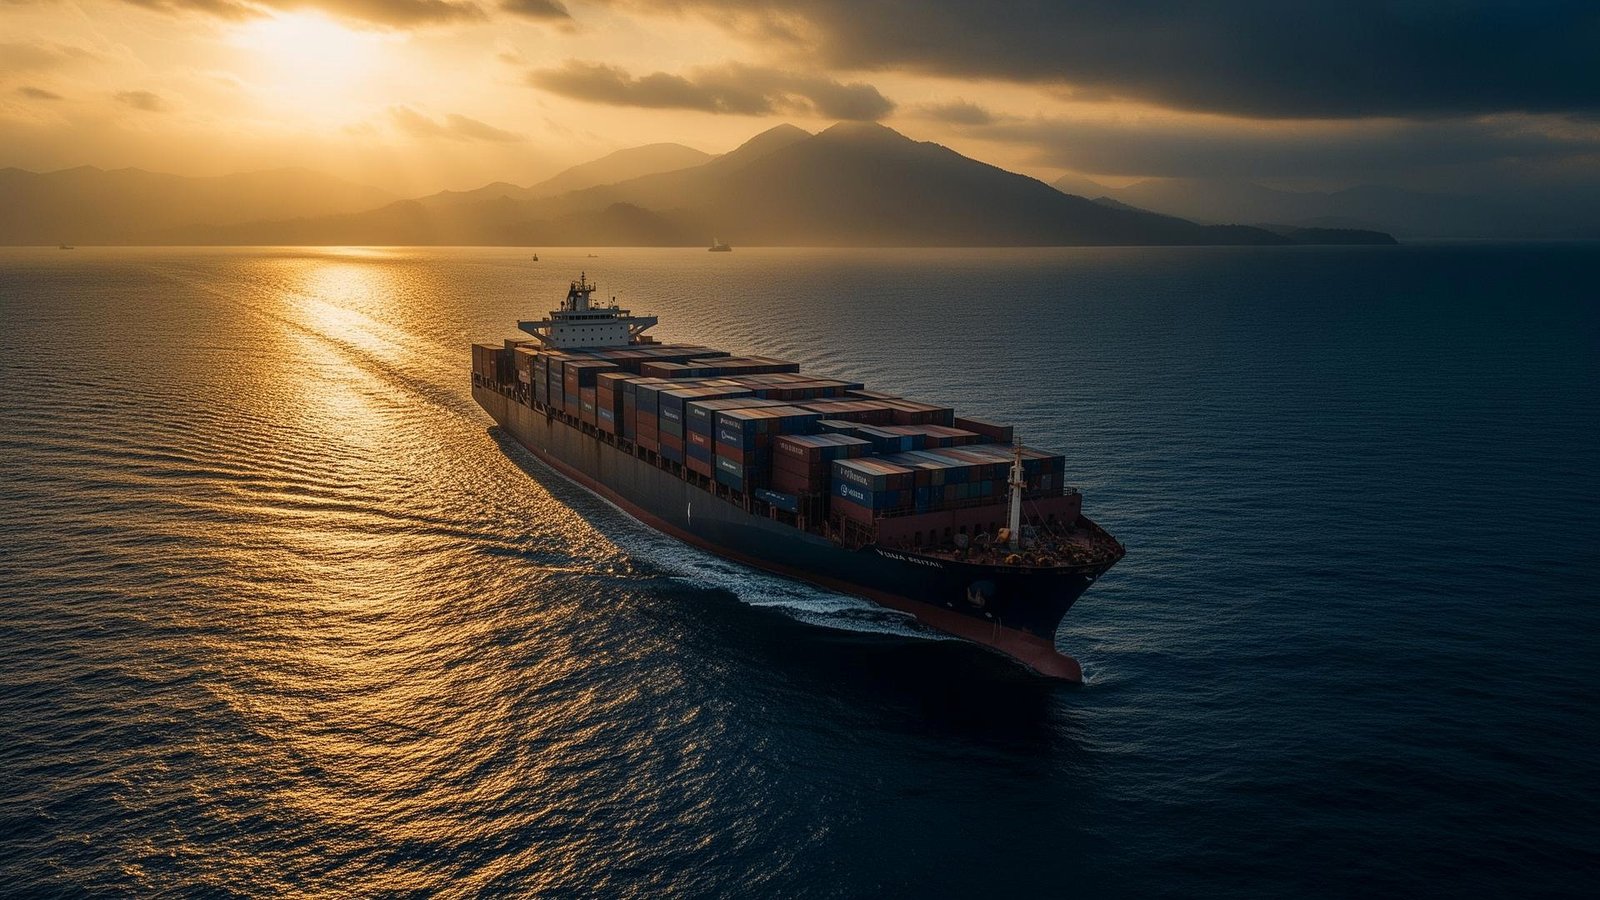
- Hormuz blockade: A US Navy MH-60 helicopter fired Hellfire missiles at the Iran-bound container ship Vela Nova on 11 August; US forces have redirected 55 vessels, disabled three and boarded two since the blockade began in mid-July. Hormuz transits fell to 16 ships on 11 August.
- Insurance: Gard P&I issued a Notice of Cancellation for war risks across the Indian Ocean, Gulf of Aden and Red Sea, expanding the existing Red Sea exclusion effective 00:01 GMT 16 August, with automatic reinstatement under revised terms.
- Bunkers: Singapore VLSFO US$844.50/mt (−US$3.00) and MGO US$1,236.50/mt (+US$26.00), diverging as distillate tightness continues even as VLSFO holds steady.
- Freight: Baltic Dirty Tanker Index 2,663 (+19); Baltic Clean Tanker Index 1,351 (−36); Baltic LPG Index surged to 19,375 (+1,686) on strong US Gulf/Japan demand.
CEO Market Commentary
Capt. Dinesh Naidu KC — Founder & Chairman, DDS Marine Group
"Two weeks ago the market was pricing a Hormuz deal. This week the US Navy fired on a ship trying to reach Iran. That is the distance between headline and reality in this trade."
Issue 002 made one argument: don't read a falling oil price as a falling risk premium, because the physical market — transits, insurance, documented routing — moves more slowly and more honestly than headlines do. This week is the clearest possible confirmation of that argument. Brent has round-tripped back above US$87/bbl, up over twelve percent in a week, as reported Hormuz de-escalation has stalled and Iran has said the Strait stays closed until its conditions are met. But the more consequential development isn't the price — it's that the standoff has turned kinetic.
A US Navy helicopter fired on a Panama-flagged container ship attempting to reach an Iranian port on 11 August. That vessel was one of 55 that US forces say they have redirected since a naval blockade against Iranian ports began in mid-July, alongside three ships disabled and two boarded. Hormuz transits have fallen to 16 ships a day. This is no longer a story about insurance premiums pricing in tail risk — it is an active, ongoing military enforcement operation in the world's most important oil chokepoint.
The insurance market has moved accordingly. Gard P&I this week issued a Notice of Cancellation for war-risk cover across the Indian Ocean, Gulf of Aden and Red Sea — not a new exclusion, but a substantial expansion of the existing Red Sea exclusion, taking effect 00:01 GMT on 16 August. Any owner or charterer with cover through Gard, or benchmarking against Gard's terms, needs to check whether their current voyage or laycan falls inside the newly excluded boundaries before that date, not after.
For Malaysia and the wider Southeast Asian region, none of this changes the underlying case we've made since Issue 001: this is a risk-allocation market before it is a freight market, and Southeast Asia's advantage is structural — proximity to the disruption without direct exposure to it — provided our own screening and documentation standards keep pace. What changes this week is the urgency. If your P&I cover runs through Gard or a similar reinsurance-linked structure, verify your war-risk terms this week. Don't wait for the renewal cycle.
Publication Principle: independent operational commentary based on publicly available market information from oilprice.com, Ship & Bunker, Hellenic Shipping News and Baltic Exchange, plus attributed broker/market colour from Wirana Shipping Corporation's Demo Market Report.
Global Oil Market
Prices and the week's directional move.
| Indicator | Latest | Reading |
|---|---|---|
| Brent crude | US$87.05/bbl | Down 2.17% intraday, 13 Aug (day pullback), but up ~12.1% from the US$79.42 close on 5 Aug. |
| WTI crude | US$81.25/bbl | Down 2.43% intraday, 13 Aug; up ~8.2% from the US$75.14 close on 5 Aug. |
| Murban crude | US$89.87/bbl | Down 0.23% intraday — Gulf grade now trading at a premium to Brent, consistent with acute Hormuz-linked supply risk. |
| US crude inventories | +17.4m bbl | EIA reported a massive build for the week ending 7 Aug — yet prices rose anyway, underlining that this rally is risk-premium, not fundamentals, driven. |
The direction has fully reversed since Issue 002. Brent closed at US$79.42/bbl on 5 August and has climbed to US$87.05/bbl intraday on 13 August — a gain of roughly twelve percent — even as EIA data shows a 17.4-million-barrel build in US crude inventories, an increase that would ordinarily pressure prices lower. That divergence is the story: the market is pricing geopolitical risk, not supply and demand. The EIA itself has raised its Brent outlook to US$87/b explicitly citing Hormuz shipping constraints.
The proximate cause is a hardening, not a softening, of the Hormuz standoff. Reporting this week describes Iran stating the Strait will stay closed until the US meets its conditions, with coverage framing the risk as building toward US$120 oil if the stalemate persists. Most significantly, the confrontation has moved from rhetoric to kinetic action.
DDS BASE CASE
We now treat the risk premium as structurally embedded rather than headline-driven. With an active US naval blockade, confirmed weapons fire, and insurers pulling war-risk cover, this is no longer a market waiting to see if de-escalation holds — it is pricing an ongoing enforcement operation with no clear end date.
Commercial effect on shipping: rising crude and bunker costs compound directly with this issue's war-risk and insurance developments. Owners and charterers with Gulf, Red Sea or Indian Ocean exposure should actively re-verify — not assume — that war-risk premiums, K&R cover and P&I terms reflect the current situation.
Crude Tanker Market
VLCC, Suezmax and Aframax directional assessment.
| Segment | Current Tone | Primary Driver |
|---|---|---|
| VLCC | Mixed, Hormuz-constrained | Active US naval blockade; transits down to 16 ships/day |
| Suezmax | Firm, Black Sea premium | TD6 Black Sea/Med up on renewed Ukrainian port attacks |
| Aframax | Mixed, regionally exposed | Softer North Sea/Med; firmer US Gulf/Caribs legs |
VLCC. The Baltic Dirty Tanker Index rose 19 points to 2,663 on 11 August, but the VLCC segment itself was mixed: TD3C (Middle East Gulf/China) eased to Ws481.67 (−6.11), while VLCC TCE across TD3C, TD15 and TD22 slipped to US$237,495/day (−US$3,281). That softness sits against a hardening physical backdrop — Hormuz transits fell to 16 ships as the US naval blockade intensified.
Suezmax. The firmest crude segment this week. TD6 (Black Sea/Med) rose to Ws577.78 (+5.28), or US$440,948/day, and TD27 (Guyana/ARA) jumped to Ws188.69 (+7.58). Suezmax TCE across TD6 and TD20 rose to US$262,925/day (+US$5,002). The strength lines up with this week's attack on major Russian grain export terminals in a Ukrainian Black Sea port strike.
Aframax. The softest crude segment, with TCE down to US$74,077/day (−US$1,154). TD7 (North Sea/UK-Cont) fell to Ws203.33, and TD19 (Cross Med) eased to Ws208.06. Against that, US Gulf/Caribs legs firmed — TD9 (Caribs/USG) to Ws340.83 — while Houthis renewed attacks on Saudi energy assets.
DDS VIEW
The crude tanker complex is showing the split we'd expect from an escalating chokepoint crisis layered on a still-adjusting Black Sea market: Gulf-exposed VLCC softening slightly even as headline risk rises, Black Sea-linked Suezmax firming on renewed terminal attacks, Aframax bifurcating between a weaker Europe and firmer Americas. TD rates move on realised fixture activity, which lags the compliance and insurance response by days — we'd expect the next print to show more of the blockade's effect.
Clean & Product Tankers
The Baltic Clean Tanker Index fell 36 points to 1,351 on 11 August, a broad-based softening across almost every route. LR2 led the complex lower: TC1 (Middle East Gulf/Japan) eased to Ws520.00, US$139,434/day, while TC20 (ME Gulf/UK-Cont) fell to US$108,137/day on a sharply lower lumpsum. The MR segment was the weakest link — the MR Atlantic Basket dropped to US$13,118/day (−US$3,966), with TC2_37 (UK-Cont/USAC) turning negative at −US$2,211/day.
| Segment | This Week's Signal | Watch |
|---|---|---|
| LR2 | Softer on ME Gulf/Japan and ME Gulf/UK-Cont, but still the highest-earning clean segment by a wide margin. | Whether Hormuz transit disruption starts constraining LR2 availability even as spot rates ease. |
| MR | Broadly weak across UK-Cont/USAC, USG/Brazil and US Gulf routes; MR Atlantic Basket down nearly 30% week-on-week. | Port congestion and arbitrage economics as bunker costs diverge (VLSFO down, MGO sharply up). |
| Handysize | Softer across Algeria/Euro Med and ARA/UK-Cont routes. | Regional supply/demand balance less exposed to Gulf headline risk. |
DDS VIEW
The Baltic Clean Tanker Index falling 36 points in the same week that dirty tanker rates and crude prices both rose is a genuine divergence worth flagging, not just noise. It suggests product tanker owners are seeing softer near-term demand even as the crude complex reprices geopolitical risk higher — possibly reflecting refiners drawing down existing product stocks rather than committing to fresh long-haul replacement cargoes while the Hormuz situation remains this fluid.
Bunker Market — Singapore & Global Benchmark
Current indications in US$/mt, 13 August 2026.
| Grade | Singapore Price | Day Change | Recent High | Recent Low |
|---|---|---|---|---|
| VLSFO | US$844.50/mt | ▼ −US$3.00 | US$875.00 | US$807.00 |
| MGO | US$1,236.50/mt | ▲ +US$26.00 | US$1,313.50 | US$1,200.00 |
| IFO380 | US$635.50/mt | ▼ −US$3.50 | US$650.00 | US$625.00 |
Singapore's bunker complex diverged sharply this week: VLSFO eased US$3.00 to US$844.50/mt while MGO jumped US$26.00 to US$1,236.50/mt — a widening VLSFO/MGO spread that points to acute distillate tightness even as residual fuel holds steady. Singapore's MGO move was among the largest of any port tracked this week, alongside Hong Kong (+US$28.00) and New York (+US$25.50). The regional pattern is mixed rather than uniformly firm: Fujairah's VLSFO fell US$13.50 even as Hong Kong and Santos rose double digits.
Compliance cost note: the EUA-VLSFO equivalent surcharge sits at roughly US$303/mt this week (EUA at €82.29), with EUA-MGO at US$309/mt — both should be reflected explicitly in bunker and freight clauses for EU-linked calls.
Geopolitical & Route Risk
Hormuz, Red Sea, Bab el-Mandeb and the Black Sea / Sea of Azov.
| Area | Current Signal | Commercial Consequence |
|---|---|---|
| Strait of Hormuz | Active US naval blockade against Iranian ports since mid-July; US Navy fired on an Iran-bound container ship on 11 Aug; transits fell to 16 ships/day. | Materially elevated hull-war and detention risk; expect delays, boardings and possible disabling for non-compliant routing. |
| Bab el-Mandeb / Red Sea | Transits down to 36 ships (from 40) on 11 Aug; Houthis renew attacks on Saudi energy assets. | Gard P&I war-risk cancellation directly covers this corridor from 16 Aug. |
| Indian Ocean / Gulf of Aden | Gard P&I issued Notice of Cancellation for war-risk cover across this zone, expanding the existing Red Sea exclusion. | Cover lapses 00:01 GMT 16 Aug and is automatically reinstated under new, narrower terms — verify laycan timing against this date. |
| Black Sea | Major Russian grain export terminals hit in a fresh Ukrainian Black Sea port attack this week. | Continued Suezmax/Aframax tonne-mile support. |
The Hormuz blockade turns kinetic. The number of ships transiting the Strait of Hormuz fell to 16 on 11 August after US Central Command said the US Navy had engaged a container ship. A US Navy MH-60 helicopter fired two Hellfire missiles at the Panama-flagged container ship Vela Nova, which had sailed from Jawaharlal Nehru Port in India on 6 August and was heading toward Iran in violation of the US blockade, according to CENTCOM. CENTCOM said US forces have redirected 55 commercial vessels attempting to run the blockade since it began in mid-July, disabled three others, and boarded two. Total crossings through the naval blockade line rose to 60 ships on 11 August from 50 the previous day — traffic is still moving, but under active US naval enforcement rather than free transit.
Insurance market response — Gard P&I war-risk cancellation. Gard's P&I entities received Notice of Cancellation from their reinsurers on 12 August covering war risks in the Indian Ocean, Gulf of Aden and Red Sea, and have in turn issued cancellation notices on the affected covers — including P&I for charterers and traders, comprehensive general liability, charterers' bunkers cover and crew cover. This is not a new exclusion but an expansion of the existing Red Sea exclusion from Member Circular 19/2023. Cover is cancelled effective 00:01 GMT on 16 August and is automatically reinstated at the same moment under a revised clause excluding the Indian Ocean, Gulf of Aden and Red Sea as newly and more broadly defined — the exception for coastal waters within 12 nautical miles no longer applies to the Bab el-Mandeb Traffic Separation Scheme or the Saudi and Yemeni Red Sea coasts. Gard's mutual P&I Excess War Risks cover is unaffected.
DDS RISK LEVEL: SEVERE
This is no longer a diplomatic standoff pricing risk into freight; it is an active naval enforcement operation with confirmed weapons fire, alongside a market-wide war-risk insurance response taking effect 16 August. No Hormuz, Red Sea, Gulf of Aden or Indian Ocean fixture should proceed without verified, current-week insurance and routing confirmation — not documentation from before 11 August.
Sanctions & Compliance Watch
Regulatory & insurance developments — week ending 13 August 2026
- Gard P&I, 12 August 2026: Notice of Cancellation issued for war-risk cover across the Indian Ocean, Gulf of Aden and Red Sea, expanding the existing Red Sea exclusion. Effective 00:01 GMT 16 August, with automatic reinstatement under the revised, narrower coastal-waters exception.
- US Navy / CENTCOM, 11 August 2026: Confirmed use of force against a vessel attempting to breach the Iran-ports blockade in effect since mid-July — the clearest signal yet that this is an actively enforced military operation, not a diplomatic posture.
- United States (OFAC), ongoing: Issue 002 covered OFAC's 29 July designation of Persian Gulf Marine Insurance Company, HormuzSafe Marine Services Authority, and tankers YEHOPE and WELL SAIL as part of the Shamkhani network. No material update this week, but the underlying concern — coerced "insurance"/toll payments to sanctioned Hormuz intermediaries — remains directly relevant given this week's legitimate insurance market disruption.
Editorial & verification note: DDS Marine Group publishes officially designated vessel names, IMO numbers and ownership details, and insurer notice terms, only after verifying them directly against primary sources — the OFAC SDN list, Treasury press releases, and insurers' own circulars.
| Control | Minimum Action |
|---|---|
| War-risk cover verification | Confirm current P&I war-risk terms against the Gard 16 August effective date if transiting the Indian Ocean, Gulf of Aden or Red Sea — do not rely on cover confirmed before 12 August. |
| Vessel screening | Screen IMO, current and former names, flag history, ownership, management, operator and ISM company. |
| Counterparty KYC | Verify beneficial ownership, directors, trading history, address, banking and sanctions nexus. |
| Hormuz blockade compliance | Confirm any Iran-bound or Iran-linked voyage plan against the current US naval blockade line before departure. |
| Record preservation | Keep screenshots, reports, approvals, emails, SOF and operational instructions in the job file. |
Southeast Asia & STS Operations
This week's global data reinforces, rather than changes, the structural case set out in Issue 001: as Middle East and Black Sea routing both become less predictable, Southeast Asia's position astride the Strait of Malacca and the Singapore Strait gives it an early, practical read on how owners and charterers are actually adjusting. This week's evidence includes Thailand's 62% increase in Hormuz-linked imports as refiners diversified sourcing, and Singapore's continued position as a comparatively firm Asia/Pacific bunkering hub.
| Market | Why It Matters to Tanker & STS Operators |
|---|---|
| Malaysia | Home to Port Klang, Malacca, Muar, Linggi and the Johor STS/bunkering corridor — the physical base of DDS Marine Group's operations. |
| Singapore | The region's principal bunkering, storage and blending hub; MGO up US$26/mt this week on distillate tightness even as VLSFO held broadly steady. |
| Indonesia | Batam and Karimun sit directly opposite the Singapore Strait and remain active in STS, bunkering and offshore support. |
| Thailand | Recorded a 62% rise in imports of Hormuz-linked strategic products in April, per ITC data — direct evidence of trade diversion benefiting the region. |
| Vietnam | Growing product-import demand and a bellwether for intra-Asia clean tanker and MR trading patterns. |
DDS VIEW
Southeast Asia is benefiting from Middle East and Black Sea disruption without being directly exposed to either conflict zone — a genuine structural advantage, provided the region's own screening, documentation and STS execution standards stay ahead of the volume it is absorbing.
Freight & Rate Signals
Baltic Exchange dirty, clean, LPG and LNG indices, 11 August 2026 — restoring attributed fixture data as promised in Issue 002.
Baltic Dirty Tanker Index — 2,663 (+19)
| Route | Rate | US$/day |
|---|---|---|
| TD3C — ME Gulf/China (VLCC, 270k) | Ws481.67 (−6.11) | 487,420 (−7,582) |
| TD2 — ME Gulf/Singapore (VLCC, 270k) | Ws507.44 (+8.00) | 528,362 (+7,717) |
| TD6 — Black Sea/Med (Suezmax, 135k) | Ws577.78 (+5.28) | 440,948 (+3,421) |
| TD7 — North Sea/UK-Cont (Aframax, 80k) | Ws203.33 (−4.59) | 96,583 (−6,218) |
Baltic Clean Tanker Index — 1,351 (−36)
| Route | Rate | US$/day |
|---|---|---|
| TC1 — ME Gulf/Japan (LR2, 75k) | Ws520.00 (−2.50) | 139,434 (−1,297) |
| TC17 — ME Gulf/E Africa (MR, 35k) | Ws492.14 (−7.15) | 54,819 (−1,383) |
Baltic LPG Index — 19,375 (+1,686), led by BLPG3 (US Gulf/Japan) at US$287.167/mt (+29.667), worth US$171,116/day.
DDS VIEW
The LPG index's jump of 1,686 points is the standout number this week — BLPG3 (US Gulf/Japan) alone gained nearly US$23,000/day. Set against a softening clean index and a dry bulk market that has fallen for a third straight day, the freight complex is fragmenting by segment: Black Sea-linked crude firm, Gulf-exposed clean soft, gas carriers picking up dislocation elsewhere.
Full route-by-route detail is available in the downloadable PDF.
Ship Recycling & Demolition Market
New standing section, sourced from Wirana Shipping Corporation's Demo Market Report. Recycling and demolition sit at the other end of the tanker lifecycle from the fixture data elsewhere — the same sanctioned and ageing tonnage in our Compliance Watch often ends its life on the beaches of the Indian subcontinent.
| Market | This Week's Signal |
|---|---|
| India | Steel market improved for a second consecutive week; recycler prices held steady. Outlook: recycler prices expected to improve. |
| Pakistan | Steel and recycler prices flat. New enforcement powers under the Environmentally Sound Management of Inventory of Hazardous Materials on Ships Bill 2026. Outlook: unchanged. |
| Bangladesh | Steel market slow; recycler prices softened US$10–15/LT LDT. Letter-of-Credit difficulties reported for importers. Outlook: prices under pressure. |
| Turkey | Steel market stable; Lloyd's Register newly authorised as Recognized Organization for DASR issuance under HKC. Outlook: unchanged. |
Circulation of new recycling candidates remained slow, drawn mainly from the dry bulk segment; sanctioned tanker tonnage continues moving to India on a regular basis, though in limited numbers at any one time. Indian beaching volumes fell sharply year-on-year (from 11 vessels/111,276 LDT in August 2025 to just 1 vessel/43,402 LDT this August), against firmer Bangladesh and Pakistan pricing.
DDS VIEW
The year-on-year drop in Indian beaching volumes, against firmer Bangladesh and Pakistan pricing, is worth watching as a leading indicator of tonnage flow. With sanctioned tankers reportedly moving to India "on a regular basis," recycling flows cross-check this issue's sanctions themes.
Seven-Day Outlook — 14–20 August 2026
| Market | Base Case | Upside Risk | Downside Risk |
|---|---|---|---|
| Crude oil | Continued strength/volatility in a US$80–95/bbl range while the Hormuz blockade remains active. | A confirmed de-escalation and stand-down of the naval blockade, unlocking transit volumes. | A further military incident, or an attack on Gulf export infrastructure, pushing toward the US$120/bbl case. |
| VLCC | Mixed rates despite elevated risk; watch for the blockade's effect to show up in the next Baltic print. | Blockade stand-down releasing pent-up Gulf loading demand. | Further vessel engagements deterring owners from Gulf-transiting fixtures altogether. |
| Suezmax / Black Sea | Firm on continued Ukrainian attacks on Russian Black Sea export infrastructure. | Further terminal strikes extending Suezmax tonne-mile demand. | A ceasefire or lull in Black Sea attacks easing the route premium. |
| Insurance / P&I | Gard's 16 Aug war-risk cancellation takes effect; other clubs likely to review Hormuz/Gulf of Oman terms. | Coordinated industry response improving clarity on standard terms. | Further clubs following Gard, tightening cover and raising premiums across the board. |
| Bunkers | MGO/distillate tightness persists; VLSFO broadly range-bound. | A reversal of the crude rally easing bunker costs. | Distillate tightness spreading further, pushing MGO higher still. |
Watch list: whether the US naval blockade escalates further, de-escalates, or holds steady; whether other P&I clubs follow Gard's lead ahead of the 16 August effective date; further Ukrainian strikes on Russian Black Sea terminals; whether next week's Baltic indices show the Hormuz transit collapse feeding through into VLCC and Aframax rates; whether the LPG index's sharp jump is a one-off or a trend.
DDS CONCLUSION
This week validated the caution urged in Issue 002: the gap between financial-market optimism and physical-market risk closed the hard way, with a confirmed US Navy engagement and a market-wide war-risk insurance response. The operator's task now is straightforward but urgent — verify, don't assume, that insurance, routing and screening reflect this week's developments, not last week's headlines.
Sources & Disclaimer
This issue draws on oilprice.com, Ship & Bunker, Hellenic Shipping News, Baltic Exchange and Wirana Shipping Corporation's Demo Market Report. Full source-by-source attribution appears in the downloadable PDF.
This publication is for general information only and is not investment, legal, sanctions, insurance, technical, navigational or chartering advice. Market indications can change without notice. Users must independently verify all data and obtain appropriate professional advice before acting. DDS Marine Group accepts no liability for decisions made solely on the basis of this publication.
Want the complete data set?
The full PDF includes fixture-level detail, the complete multi-port bunker matrix and full source attribution.